 LOGIN

 VN
 Sea Freight
 Air Freight
 Intermodal
 Customs Brokerage
 Project Logistics
 Warehouse Services
 Trucking
 Insurance
 Logistics Infrastructures
 Consulting & Assistance
 NVOCC
 Barge & Coastal Feeder
 GSA / PCSA Airlines
 Perishable / Refrigerated Logistics
 Dangerous Good Logistics
 Oil & Gas Logistics
 Offshore Services
 Rice Logistics
 Global Sales Logistics
 Parcel / Courier Logistics
 Cross-Docking & End-To-End Warehousing
 On Board Courier
 Buying Agent

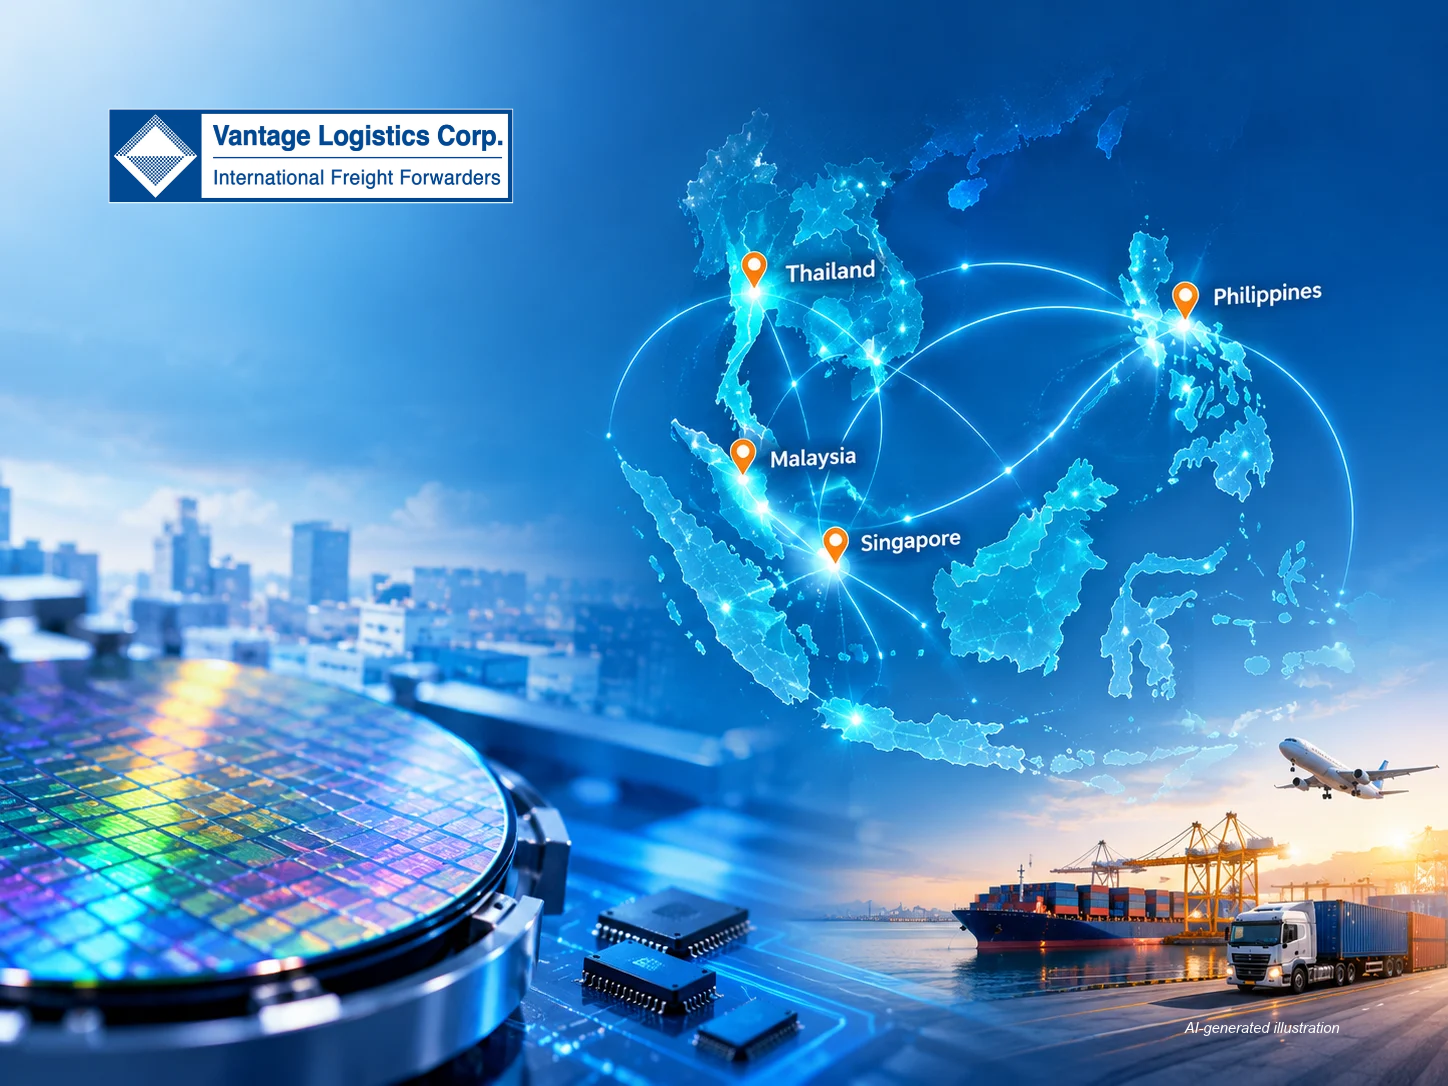
The wave of investment in semiconductors and advanced electronics is expanding rapidly across Southeast Asia. Division of labor among nations is becoming increasingly defined, reflecting the distinct roles each market plays within the regional supply chain.
Overview of Key Markets
| Market | Highlighted Data & Events | Role in the Value Chain |
| Thailand | 880 registered projects ($26.8B, 2023–H1/2026) | Expanding electronics, components & PCB ecosystem |
| Malaysia | RM16.9B in semiconductor investment approved (2025) | Strengthening Assembly, Testing & Packaging (ATP) |
| Singapore | Micron broke ground on $24B wafer fab (Jan 2026) | Concentrating on high-tech front-end fabrication |
| Philippines | $26.12B in electronics exports (H1/2026) | Maintaining scale in electronics & component exports |
(Alongside these markets, Viet Nam continues to serve as a vital hub for regional assembly, testing, and packaging operations).
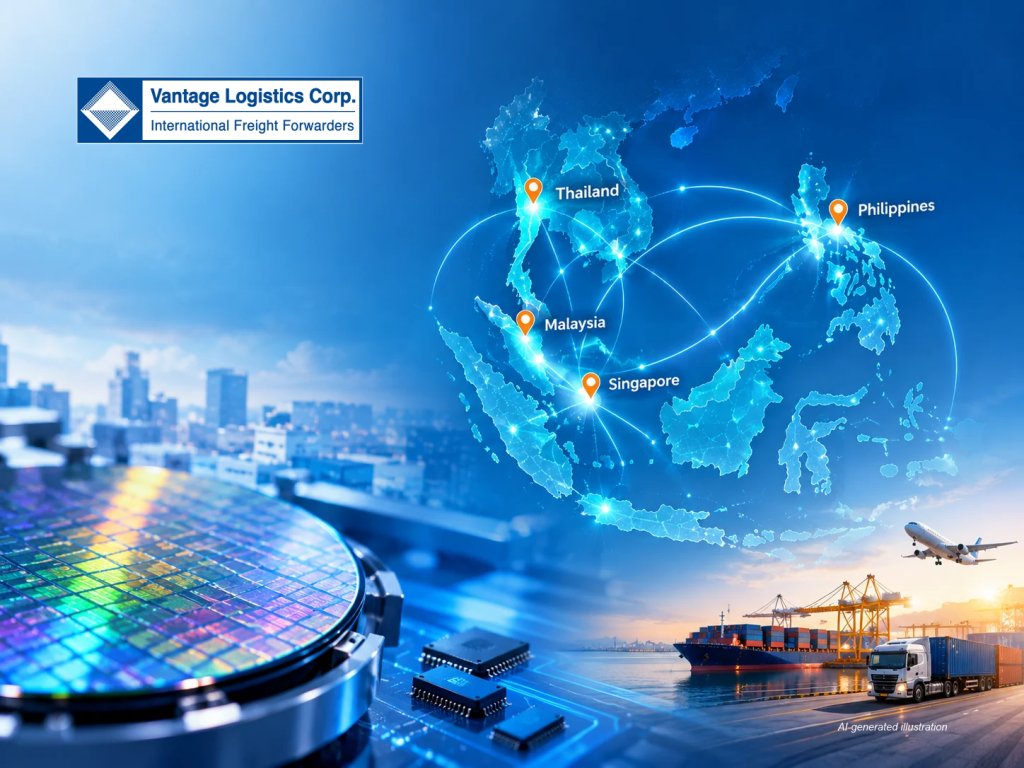
Thailand Expands Investment in Electronics and Semiconductors
From 2023 through the end of June 2026, the Board of Investment of Thailand (BOI) recorded approximately 880 project applications for investment incentives in semiconductors and advanced electronics, representing a total registered capital of roughly $26.8 billion.
The project portfolio spans from semiconductors, printed circuit boards (PCBs), and hard disk drives (HDDs) to AI servers, networking equipment, and electronic components. Notably, the PCB sector alone accounted for 224 projects worth approximately $9.85 billion.
This data indicates that Thailand is aiming for a broader electronics ecosystem rather than focusing solely on chip manufacturing. However, these figures represent proposed or registered applications and do not fully reflect pledged capital that has been disbursed or operational capacity already brought online.
Manufacturing Hubs Assume Distinct Roles
The development of the ASEAN semiconductor industry is not following a uniform template. Each market possesses its own industrial baseline and investment trajectory.
- Malaysia (Expanding Semiconductor Investment): In 2025, Malaysia approved RM28.5 billion in investments for the Electrical & Electronics (E&E) sector, with the semiconductor segment alone securing RM16.9 billion. As a long-established regional hub for assembly, testing, and packaging (ATP), these new inflows demonstrate its enduring appeal – though approved investment values do not immediately translate into operational production capacity
- Singapore (Scaling Wafer Manufacturing Capacity): In January 2026, Micron broke ground on an advanced wafer fabrication facility in Singapore, backed by a planned $24 billion investment over 10 years (with production expected to commence in H2 2028). The project underscores Singapore’s position in leading-edge, high-tech manufacturing stages
- Philippines (Maintaining Role in Electronics Exports): In the first half of 2026, the Philippines exported $26.12 billion in electronic products, accounting for 55.8% of its total export value. While representing a major share, this category encompasses a wide variety of goods and cannot be construed strictly as pure semiconductor export data.
ASEAN in the Global Semiconductor Supply Chain
According to the ASEAN Investment Report 2025, ASEAN accounts for over 20% of global back-end semiconductor activities, including assembly, testing, and packaging. Meanwhile, front-end operations such as wafer fabrication are concentrated more heavily in Singapore and Malaysia.
Rather than pursuing a single unified manufacturing model, multiple ASEAN economies are expanding across different links of the semiconductor value chain – ranging from wafer fab to assembly, testing, and associated electronics manufacturing.
Although many multinational corporations operate facilities across several ASEAN nations, this presence does not automatically imply direct inter-factory transactions or integration into a single closed supply chain. Assessing actual regional synergy requires analyzing broader trade data, input supply sources, and individual corporate customer networks.
New Investments and Cross-Market Connectivity Demand
As new projects transition into deployment, logistics demand will shift based on product category, plant location, and supplier architecture. For logistics providers and international partners, three core sets of indicators warrant close monitoring:
- Project Operational Progress: The precise timing of plant commissioning and the actual pace of capacity expansion
- Inter-Market Goods Flow: The value and trade structure of components exchanged between manufacturing hubs (verified through import/export trade data reconciliation)
- Transport Connectivity Requirements: Shipping routes, lead times, specialized handling requirements, and cross-border customs procedures tailored to specific product categories
These indicators will help differentiate between a market that is merely “attracting paper capital” and a mature production network generating stable freight flows.
Conclusion
Investment in semiconductors and electronics continues to expand across ASEAN, yet the region is not developing as a monolithic manufacturing monolith. Instead, the region is evolving toward a polycentric model: Singapore focuses on high-tech front-end processes, Malaysia maintains its stronghold in the back-end semiconductor ecosystem, the Philippines sustains its large-scale electronics exports, while Thailand broadens its capability across component and PCB manufacturing.
For supply chain professionals and global partners, project implementation speed, actual operational capacity, and cross-border trade flows will serve as far more meaningful indicators for evaluating regional connectivity than announced capital commitments alone.
Contact Vantage Logistics for tailored transport solutions and competitive quotations.
Please provide details on cargo type, market, origin, destination, and estimated timeline.
| Vantage Logistics Corp – South East Asia (S.E.A) Logistics Provider
One-Stop Shop For Integrated Logistics Services |
|
| Head Office | Viet Nam – Suite 6.01, Floor 6th, Block A, RiverGate Residence,
151-155 Ben Van Don, Khanh Hoi Ward, HCMC, Viet Nam |
| Branch | Thailand, Laos, Cambodia, Malaysia, Indonesia, Singapore |
| Contact Us | |
| in**@*****om.vn | |
| Hotline | +84-909-026-261 |
| Website | https://vantage-logistics.com |
Send your shipment enquiry today and receive a tailored transport plan from the Vantage Logistics team.
 Vantage News


